7 Likes


SB1
We reiterate our Buy recommendation and TP of NOK20/sh on Nekkar after the 2Q26 figures. We make significant estimate revisions. While the estimate changes look extreme with revenue estimates down 9%/18%/8% in 26e-28e and EBITDA down 26%/32%/3% in the same period, we argue this is driven by i) updated 2026e tender pipeline on Syncrolift which leads to delayed pipeline conversion, ii) Globetech’s acquisition of Satco, and iii) an assumption of zero activity in Techano Oceanlift past 2026. This is more of a reset from our side and every shiplift award to Syncrolift NTM will lead to a positive estimate revision from our side. Nekkar currently trades at EV/EBITDA, EV/EBIT and P/E of 5.3x/5.9x/8.5x on our 2028e. Our SOTP on 2028e points to NOK20.1/sh, which is our TP.Our Analysis
Syncrolift timing pushed out: The newbuild tender pipeline stands at NOK700m/NOK5bn/NOK3bn (26e/27e/28e+). The thin 2026 tender bucket means few incremental awards land this year, even with firm backlog front-loaded at ~NOK455m in 2026/27 (vs NOK198m in 2028+). We therefore cut Syncrolift revenue 18% in 2026e and 29% in 2027e, respectively. This lowers our EBITDA 25% and 29% in the same period. We now model only reported backlog on Syncrolift as the basis for Syncrolift in 2026 and 2027, a deliberately conservative approach that leaves each new order NTM as a positive estimate revision, given that Syncrolift has been awarded two shiplifts in the past three months.We place zero value on Techano: The last reported order backlog stands at NOK33m, with no order intake in the last year. We therefore expect the division to be divested or wound down unless it can secure attractive, i.e. profitable, projects. Consequently, we model a full stop once the company has delivered its last crane, with zero revenue thereafter under our assumption of no further activity. We value the segment at zero in our SOTP and model a negative EBITDA contribution of NOK8m in 2027e.
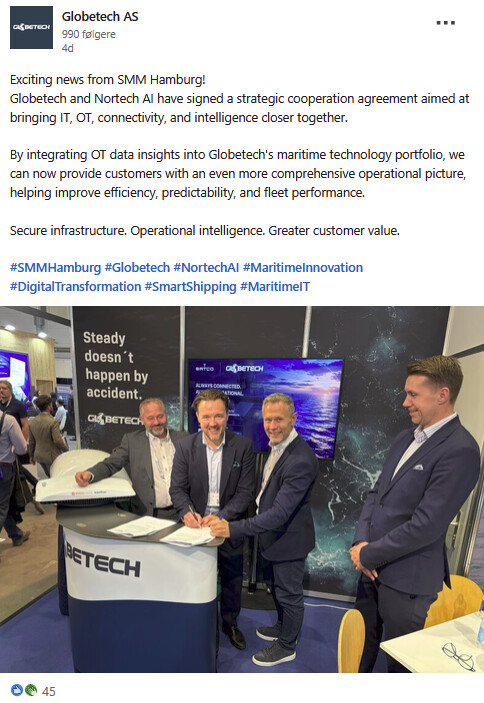
Other estimate revisions driven by Globetech acquisition: In August, Globetech acquired 60% of Satco AS, a provider of navigation, connectivity and CCTV systems to shipping and offshore. We view this as an excellent bolt-on with potential for recurring revenues and cross-sales. Globetech bought 60% of Satco at a low single-digit EBITDA multiple, implying roughly NOK25-50m EV for 100% on ~NOK12m EBITDA, with the remaining 40% deferred to 2029 on an earnings-based earn-out and funded from Globetech’s own cash. From this, we increase Globetech revenue by 10-36% in 26-28e, while EBITDA is revised up by 11-27% in the same period.
Our SOTP points to NOK20.1/sh compared to the current price of NOK14.3/sh: Nekkar currently trades at EV/EBITDA, EV/EBIT and P/E of 5.3x/5.9x/8.5x on our 2028e. Our SOTP based on 2028e implies NOK20.1/sh, which we use as the basis for our TP.
8 Likes
6 Likes
01/09:

Liker at utenlandsk media plukker opp ting fra Nekkar Q&A 
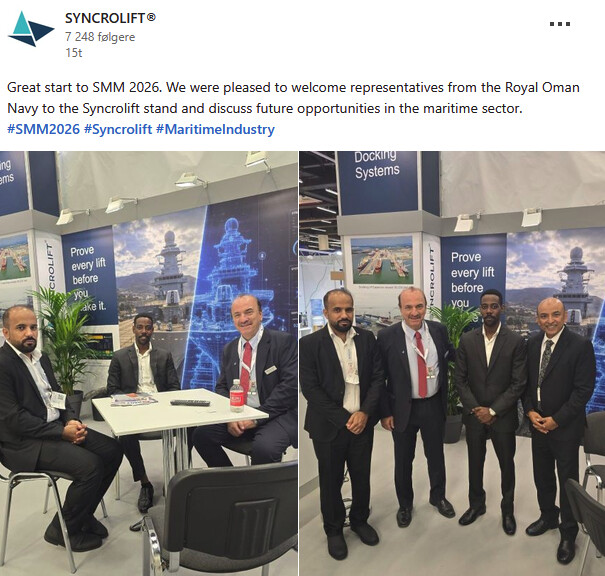
Spennende besøk i Hamburg også, spesielt når man vet det planlegges ting i Oman
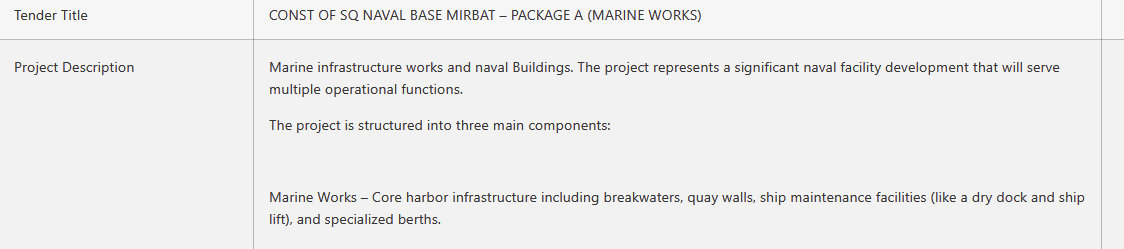
https://www.bncnetwork.net/project/None/MzQzNTA5/
Fortsettes offbooks i dag også
02/09:

6 Likes
Lov å håpe på at tilbudssiden er tom snart.
Regner med at det er Ølberg som kvittet seg siste rest i dag og har de 3 siste offbooks handlene (70k igår + 289892 i dag)


Fokuset her er vel hovedsakelig på større båter, men øker vel uansett muligheten for at noe kan dryppe på Syncrolift?
The companies are meant to use the investment to expand and modernize their plants. One of the focuses is developing advanced technologies for the next generation of advanced ocean shipping.
“These three cases represent just a small portion of the numerous investment plans submitted by various businesses, essentially the first phase,” said Kaneko.

Trodde egentlig salgssiden var tilnærmet tom, men kan se ut som det er én BNP-konto som gjenstår / bare skal ut (med siste rest til salgs i auksjonen - hvor det gikk 17 av 250k ish).
du ser at det er denne kontoen som er selger nå og ikke flere?
Kun en kvalifisert spekulasjon basert på tilgjengelige lister. De har etterslep på 2 dager (T+2), så alle forbehold inntil fasit foreligger. Det kan være en/flere andre (salgsordren i dagens auksjon var dog én).
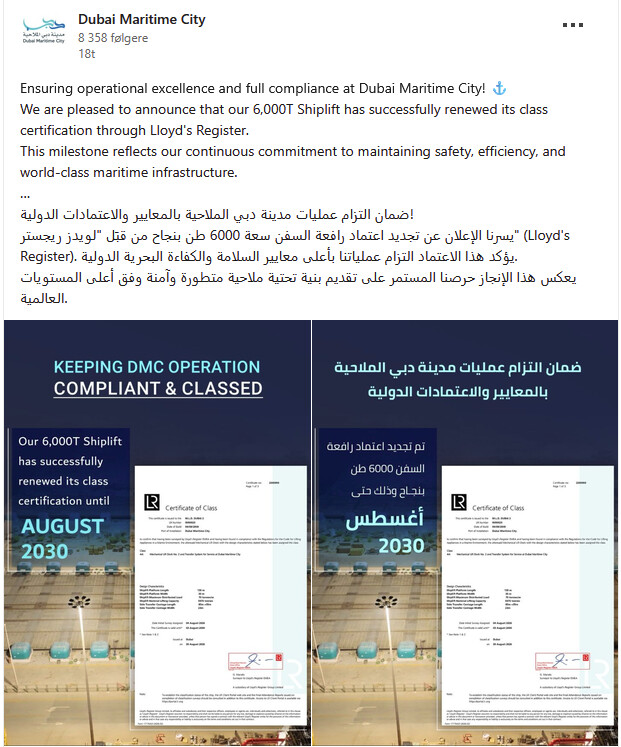
Da er JV godkjent. Burde kunne øke mulighetene for Syncrolift i India fremover mtp gode relasjoner både med Cochin (nylig installert Syncrolift@ISRF) og DP World (Dubai Maritime City)

6 Likes

(betalingsmur)
Har ikke tilgang. Vet ikke om noen av de «tre andre» som nevnes er relevant for FiiZk (og/eller om det kan bety kontrakter i vente).
4 Likes

Bardex sin linkedin fremhevet denne, like relevant her selv om Syncrolift ikke lengre satser i Amerika:
1 Like